Executive summary
Allowance volatility can reflect credit migration, portfolio mix, forecast changes, model limitations, data corrections, segmentation, recoveries, prepayments, qualitative adjustments, or management judgment. When those drivers are not separated, leadership cannot tell whether the estimate changed for an economic reason or because the process itself is unstable.
Community banks can improve defensibility by connecting data lineage, model governance, forecast decisions, qualitative-factor ownership, reconciliation, review, approvals, monitoring, and disclosure support in one repeatable evidence chain. Accounting conclusions remain the responsibility of the institution and its qualified accounting advisers.
1. Explain movement before debating the result
Create a period-over-period bridge that separates portfolio volume and mix, risk-grade or delinquency migration, charge-offs and recoveries, model or methodology changes, forecast assumptions, reversion, segmentation, data corrections, and qualitative adjustments. Each material driver should have an owner and supporting evidence.
2. Govern data at the point it enters the estimate
Identify critical data elements, authoritative sources, transformations, history, refresh timing, reconciliations, quality thresholds, overrides, exclusions, and issue treatment. A control should show not only that a check ran, but what population it covered, who reviewed exceptions, and how unresolved issues affected the estimate.
3. Separate model performance from management judgment
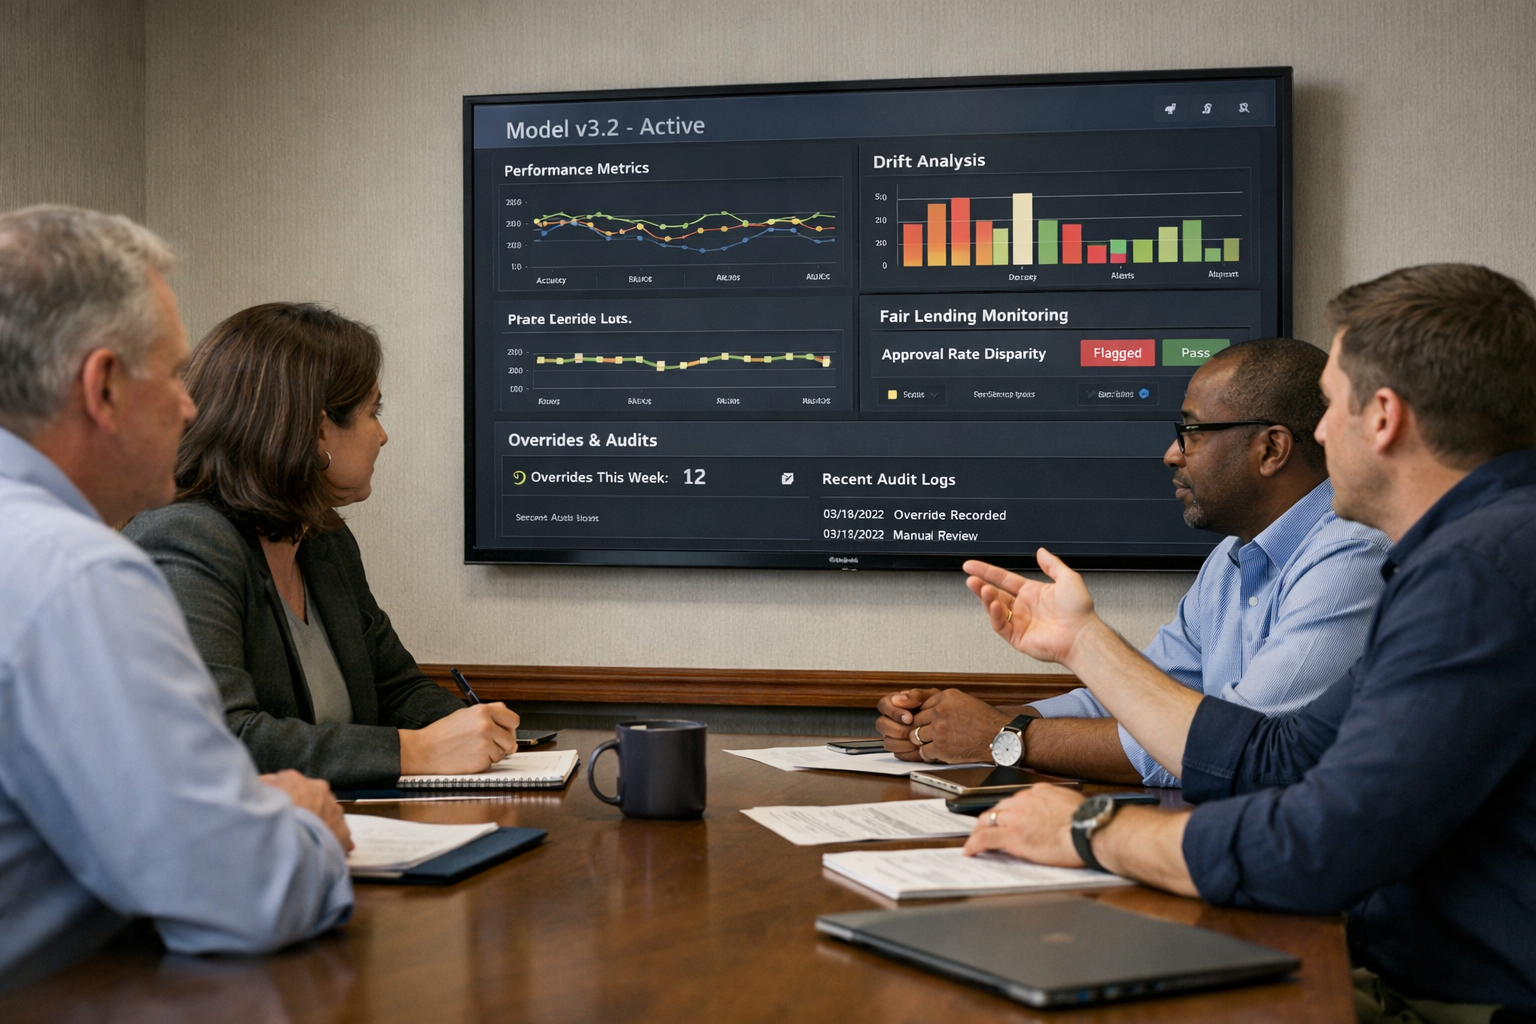
Model monitoring should assess accuracy, stability, sensitivity, segmentation, limitations, overrides, and performance under changing conditions. Qualitative adjustments should state the risk not captured, evidence considered, directional logic, magnitude rationale, overlap assessment, approval, and conditions for reduction or removal.
4. Use a disciplined forecast decision record
Document the scenarios, sources, period, reversion approach, sensitivity, alternative views, management rationale, consistency with other bank planning, challenge, approval, and subsequent comparison with actual conditions. This makes change explainable without pretending forecasts are certain.
5. Monitor the process as well as the estimate
Useful measures include late or corrected data, reconciliation breaks, unresolved model findings, overlay age, repeated manual adjustments, review rework, sensitivity concentration, approval timing, documentation exceptions, and variance between forecast assumptions and observed conditions.
Build a repeatable allowance evidence pack
A well-designed pack traces the reported estimate to source data, model versions, configurations, forecasts, qualitative adjustments, controls, exceptions, approvals, movement analysis, monitoring, findings, remediation, and disclosure support. Reviewers can focus on judgment and risk rather than reconstructing the process.
Cicrim supports banks with data governance, model-risk operations, control design, workflow, evidence architecture, monitoring, issue management, and reporting. This material is operational guidance and not accounting, legal, or audit advice.